Innovation vs Protection in Crypto Regulation: The 2025 Shift
 Sep, 21 2026
For over a decade, the U.S. crypto market was stuck in a regulatory limbo. You wanted to build new financial tools, but you didn't know if the Securities and Exchange Commission (SEC) would sue you next week for doing it. This "regulation by enforcement" approach created a chilling effect, pushing many startups offshore and keeping traditional banks on the sidelines. But something fundamental changed in 2025. We aren't just tweaking rules; we're seeing a complete reimagining of how governments interact with digital money.
The core tension has always been simple: How do you protect everyday investors from scams without strangling the technology that could revolutionize finance? Too much protection, and you kill the innovation. Too little, and you get another FTX collapse. The events of 2025 suggest we've finally found a middle ground, or at least, a path toward one. Let's look at what actually happened, why it matters, and what it means for your portfolio.
The End of Regulation by Enforcement
If you were paying attention in early 2025, you noticed a shift in tone. It wasn't subtle. On January 23, 2025, President Trump signed an executive order titled "Strengthening American Leadership in Digital Financial Technology." This wasn't just political theater. It dismantled key policies from the previous administration and established a new White House working group dedicated to digital assets. The message was clear: the U.S. wants to lead, not lag.
This move signaled a departure from the strategy where agencies like the SEC and the Commodity Futures Trading Commission (CFTC) acted as both referee and prosecutor. For years, companies had to guess which agency claimed jurisdiction over their token. Was it a security? A commodity? The answer often depended on who filed the lawsuit first. The new approach prioritizes clarity. By nominating individuals with actual crypto experience to lead these agencies-such as Brian Quintenz for the CFTC-the government acknowledged that you can't regulate what you don't understand.
Acting SEC Chairman Mark Uyeda relaunched the Crypto Task Force under Commissioner Hester Peirce, known affectionately as "Crypto Mom." Her mandate? Focus on innovation-focused objectives rather than punitive measures. This humanized the regulator's role. Instead of asking "Are you breaking the law?", they started asking "How can we help you comply while building something new?"
Crypto Week and the Legislative Breakthrough
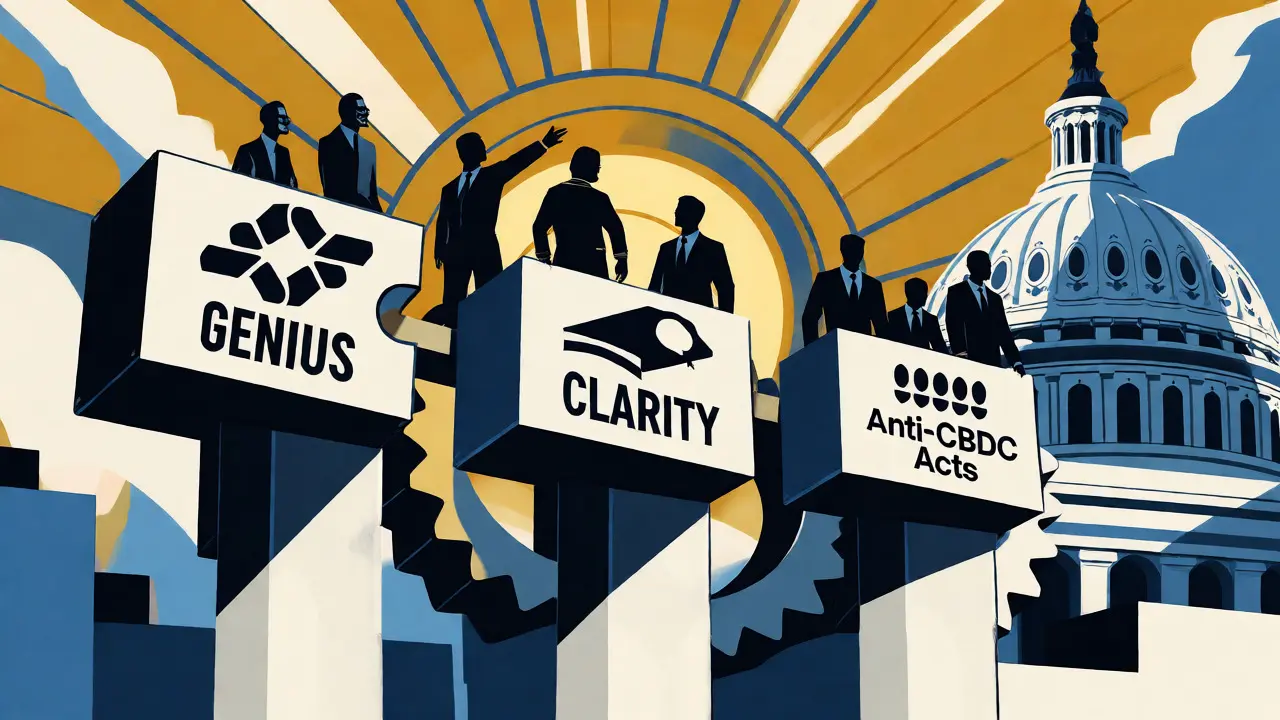
The real turning point came during what legislators dubbed "Crypto Week." Congress advanced three major bills that collectively rewrote the rulebook. These weren't vague resolutions; they were specific, actionable laws designed to solve long-standing ambiguities.
- The GENIUS Act: This became the first comprehensive federal crypto legislation signed into law. It specifically targets stablecoins, providing clear guidelines on issuance and oversight. Stablecoins are the plumbing of DeFi, so regulating them properly is crucial for stability.
- The CLARITY Act: Officially the Digital Asset Market Clarity Act, this bill aims to define which digital assets fall under securities law versus commodity law. This distinction determines which regulator oversees trading and how taxes are handled.
- The Anti-CBDC Act: This addresses concerns about a Central Bank Digital Currency, ensuring that any future dollar-backed digital currency doesn't stifle private sector innovation.
Senator Bill Hagerty described these bills as vital for keeping America at the forefront of digital asset innovation. And he’s right. When regulations are unclear, capital flees to jurisdictions with clearer rules, like Singapore or Dubai. By passing these laws, the U.S. signaled it wants to recapture that competitive advantage.
| Feature | Pre-2025 Approach | Post-2025 Approach |
|---|---|---|
| Primary Strategy | Regulation by Enforcement | Proactive Frameworks |
| Jurisdictional Clarity | Ambiguous (SEC vs. CFTC conflicts) | Defined Roles (GENIUS/CLARITY Acts) |
| Institutional Participation | Limited due to legal risk | Growing due to certainty |
| Innovation Location | Offshore (Singapore, Dubai) | Onshoring to U.S. |
| Agency Stance | Punitive/Reactive | Collaborative/Adaptive |
Balancing Innovation with Consumer Safety
Here is the tricky part: Does less enforcement mean less protection? Not necessarily. The new framework shifts the burden of proof. Previously, regulators chased bad actors after the damage was done. Now, the focus is on structural integrity. The GENIUS Act, for example, requires stablecoin issuers to maintain full reserves and undergo regular audits. This protects users from the "fractional reserve" risks that plagued earlier projects.
Compliance experts note that while the tone is friendlier, the expectations are higher. Firms must now have robust systems for governance, supervision, and documentation. It’s no longer enough to say, "We’re decentralized." If you hold user funds, you need transparent controls. This balance allows innovation to flourish within guardrails. Think of it like seatbelts in cars: they don’t stop you from driving fast, but they ensure you survive the crash.
The SEC’s "Project Crypto," led by Chair Paul Atkins, explicitly aims to modernize securities laws. Atkins called this a "sea change," directing staff to promote capital formation. This isn't just about letting crypto companies raise money; it's about integrating digital assets into the broader financial ecosystem. When traditional banks feel safe entering the space, liquidity increases, spreads narrow, and access improves for everyone.
What This Means for Investors and Builders
If you are an investor, this shift reduces one of the biggest risks in crypto: regulatory uncertainty. You can now make decisions based on fundamentals rather than fear of a sudden lawsuit. Institutional money, which moves slowly, is beginning to flow in because the legal landscape is predictable. This doesn't mean prices will only go up, but it does mean the market is maturing.
For builders, the opportunity is immense. Startups can now design products with a clear understanding of compliance requirements. You don't need to hire a team of lawyers to figure out if your token is a security. The CLARITY Act provides a roadmap. However, success depends on adapting quickly. The absence of aggressive enforcement does not mean the absence of scrutiny. Regulators are watching, but they are watching with the intent to guide, not just punish.
Consider the impact on DeFi (Decentralized Finance). Many DeFi protocols struggled to attract institutional partners because of unclear liability issues. With clearer rules, we expect to see more hybrid models where traditional finance meets blockchain efficiency. Imagine earning yield on your savings through smart contracts, backed by regulated custodians. That future is becoming reality.
Global Context and Future Outlook
The U.S. isn't alone in this race. The European Union implemented its Markets in Crypto-Assets (MiCA) regulation, offering a different but equally structured approach. China banned most crypto activities. The UK is still refining its stance. By moving decisively in 2025, the U.S. positioned itself to compete globally. If other nations see American firms thriving under clear rules, they may adjust their own policies to remain attractive.
Looking ahead, implementation is key. Laws are written on paper; enforcement happens in practice. We expect to see formal rule proposals on custody, issuance, and trading throughout late 2026. State-level oversight may also play a role, filling gaps as federal rules evolve. The goal is a unified system where digital assets are treated with the same seriousness as stocks or bonds, but with the flexibility needed for technological progress.
This transformation isn't just about money. It's about trust. For crypto to become mainstream, people need to believe that their assets are safe and that the system won't be dismantled by arbitrary government action. The 2025 reforms provide that foundation. They acknowledge that innovation and protection aren't enemies-they're partners.
Frequently Asked Questions
What was the main problem with previous crypto regulations?
The main issue was "regulation by enforcement." Agencies like the SEC and CFTC did not provide clear rules upfront. Instead, they waited for companies to launch products and then sued them if they disagreed with the classification. This created massive legal uncertainty, discouraging investment and pushing businesses offshore.
How does the GENIUS Act differ from other crypto laws?
The GENIUS Act specifically focuses on stablecoins. Unlike broader bills, it mandates strict reserve requirements and audit standards for stablecoin issuers. This ensures that tokens pegged to the dollar are fully backed, reducing the risk of de-pegging events that can destabilize the wider market.
Does less enforcement mean fewer consumer protections?
No. The new approach shifts from reactive punishment to proactive structural safeguards. Regulations now require better transparency, auditing, and segregation of customer assets. While regulators may not sue as aggressively, the baseline standards for operational integrity are higher, protecting consumers before problems occur.
Why is jurisdictional clarity important for crypto investors?
Clarity determines which agency regulates a specific asset and what tax implications apply. Without it, investors face unpredictable legal risks. The CLARITY Act helps define whether a token is a security or a commodity, allowing for consistent application of laws and making it easier for institutions to participate safely.
How will this affect traditional banks?
Traditional banks have been hesitant to enter crypto due to regulatory ambiguity. The new framework gives them the confidence to offer crypto services, such as custody and trading. This integration brings more liquidity to the market and offers retail customers familiar interfaces for accessing digital assets.